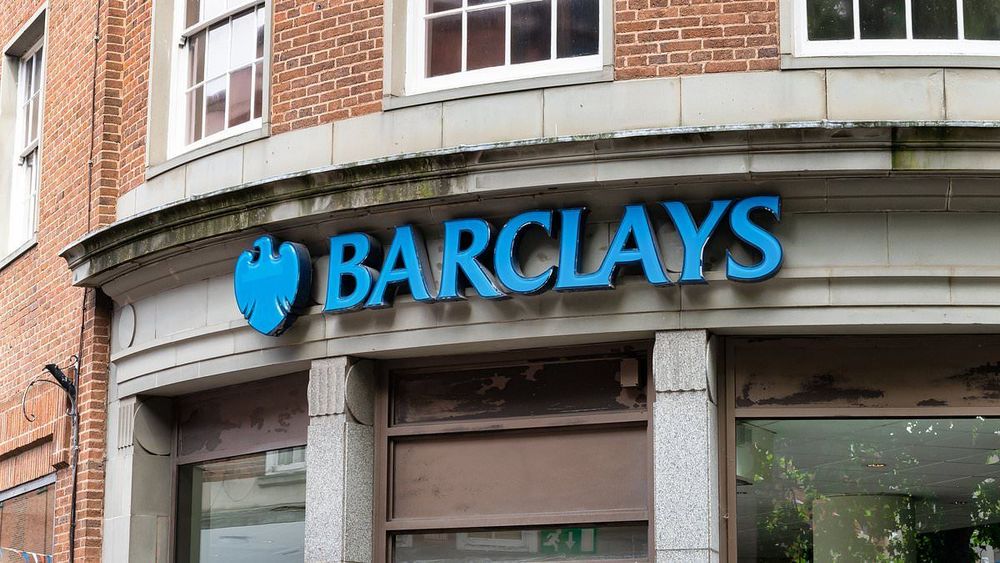
Barclays launches £750 cashback promotion for ISA transfers and life insurance
Barclays has introduced a dual cashback promotion offering up to £750 for customers who transfer an Individual Savings Account and purchase a life insurance policy through the bank. The offer runs from 8 September to 25 November 2026.
To qualify for the ISA cashback component, customers must hold either a standard or Premier current account with Barclays and transfer a minimum of £10,000 into one of the bank's fixed-rate ISA products. The cashback tiers range from £50 for transfers between £10,000 and £24,999, up to a maximum of £600 for Premier customers transferring £100,000 or more.
For the life insurance element, standard current account holders can receive £100 cashback for policies with monthly premiums of at least £10, while Premier customers qualify for £150 cashback with premiums of £12.50 or more per month. Customers must apply for the insurance and complete the purchase within six months.
Significant eligibility hurdles
The promotion comes with substantial barriers to entry. Premier current account status requires either an annual income of at least £75,000 or total balances of £100,000 or more in Barclays savings and investment products. Only transfers to Barclays fixed-rate single access or Premier triple-access ISAs qualify, and the bank does not accept transfers from its own ISA products or from lifetime ISAs, help to buy ISAs, or innovative finance ISAs held elsewhere.
The ISA market in the UK held approximately £872 billion across 21 million accounts at the end of the 2023/24 tax year, with cash ISAs representing around 41.3 per cent of the total market value at £360 billion. Around 16.8 million adult ISA accounts were subscribed to in 2024/25, up from 15 million in 2023/24, according to HMRC statistics published in September 2026.
Rate comparison reveals modest advantage
Barclays currently offers 4.3 per cent on its one-year fixed ISA. By comparison, Tandem Bank leads the market with a one-year fixed rate of 4.76 per cent. For a £10,000 transfer, Barclays would generate £430 in interest over one year, while Tandem would produce £476. When the £50 Barclays cashback is factored in, the total return from Barclays reaches £480, representing just £4 more than Tandem's offering.
This narrow margin suggests the promotion may hold greatest appeal for existing Barclays customers already considering a transfer, rather than those seeking the strongest financial return. Data from HMRC shows that only 22.7 per cent of ISA subscribers used the full £20,000 annual allowance in 2022/23, with the most common contribution band being £1-£2,499, used by 41.9 per cent of subscribers. This indicates that Barclays' minimum transfer threshold of £10,000 sits above typical ISA balances for many savers.
Understanding ISA transfer rules
Savers considering the offer should understand that ISA transfers do not count against the £20,000 annual ISA allowance for the 2026/27 tax year. Any amount from previous years' ISAs can be transferred without affecting the current year's contribution limit. However, current-year ISA contributions must be transferred in full if moved between providers, whereas previous years' ISA balances can be transferred partially.
Under UK regulatory guidelines, cash ISA transfers between providers must be completed within 15 working days, while other types of ISA transfers are expected to be completed within 30 calendar days. The Financial Conduct Authority regulates financial firms providing services to consumers and maintains the integrity of financial markets, operating independently of government.
The proportion of ISA holders in the United Kingdom increased by 2.6 per cent in 2024/25 compared to the previous year, with the average ISA market value rising from £34,044 to £37,831, representing growth of 11.1 per cent. Cash ISAs accounted for 66.2 per cent of all adult ISA account subscriptions in 2023/24, with 9.9 million cash ISA accounts actively subscribed to during that tax year.
Before committing to any cashback promotion, savers should calculate whether the combined interest rate and cashback genuinely delivers better value than alternative products available in the market. The eligibility requirements and relatively modest financial advantage mean careful consideration is essential.