One market, very different valuations
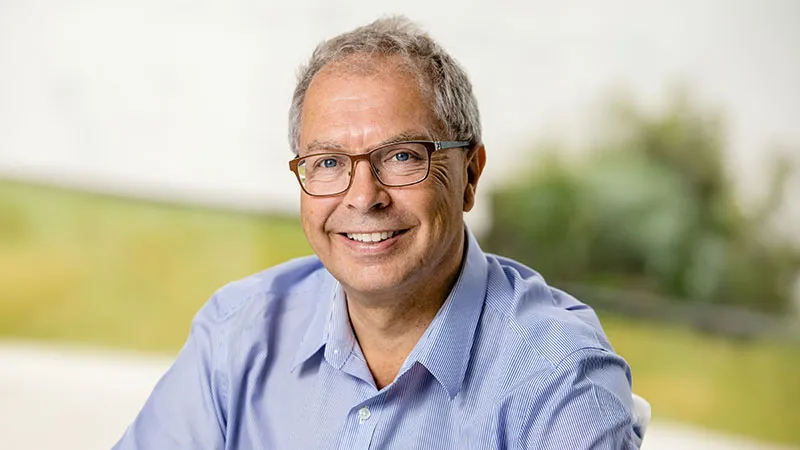
Speaking to Portfolio Adviser, de Lisle described US equities as a "curate's egg": attractive in some areas and unappealing in others. Homebuilders, for example, are trading at cyclical lows normally associated with a recession, he said, even as technology companies dominate the major indexes.
The headline measures explain investors' caution. Technology accounts for roughly 40% of the S&P 500, while its 10 biggest constituents make up nearly two-fifths of the index. Barclays data puts the US market's cyclically adjusted price-to-earnings ratio at 39 times, comparable to the dot-com bubble. De Lisle noted that the five largest US stocks alone have a combined market capitalization of almost $16 trillion (£11.9 trillion), alongside an unprecedented tilt toward technology.
Yet he rejects a simple analogy with 2000. Unlike the technology companies of that bubble, today's hyperscalers have substantial earnings, strong fundamentals and monopolies, he said.
Semiconductors are a different concern. By summer 2026, they represented 22% of the S&P 500, an unusually large share for an industry prone to booms and busts. De Lisle pointed to Micron: investors who bought at its 2000 peak waited 24 years to recover their money. Trend-following can reward investors for a time, he said, but the behavioral bias behind it can eventually cost them those gains.
A smaller-company strategy with limits on tech exposure
De Lisle regards US small- and mid-cap stocks as offering the strongest long-term return prospects with the lowest risk. His firm's focus on that part of the market dates to its founding in 2005 and rests on his belief that valuation is the most useful predictor of a stock's long-term potential.
He is CEO of De Lisle Partners and lead portfolio manager of the VT De Lisle America Fund. Its July 31, 2026, factsheet reported assets of $841 million across 164 holdings, with a weighted median market capitalization of $2.55 billion. The fund launched on August 6, 2010.
The strategy's valuation and company-size constraints exclude some of the hyperscalers that have delivered exceptional returns. But de Lisle sees other ways to invest in businesses benefiting from technology. He cited John Deere's plans to automate harvests with AI, arguing that its sophistication in this area gives it an advantage over less advanced agricultural competitors.
The fund has also reduced its direct AI exposure. In its July 2026 commentary, it said it had cut "pure play" AI positions from 13% to 10% and then to 5% as market momentum reversed. The fund lost 4.7% that month, compared with a 0.2% decline for the IA North America sector.
Longer-term results differ by period. As of July 31, the USD share class had gained 725.5% cumulatively since launch, versus 584.2% for the IA North America sector average. Over 10 years, however, its 222.0% return trailed the sector's 233.1%.
Why he is still watching Build-A-Bear
De Lisle acknowledged that inflation and rising interest rates have made conditions difficult for smaller, more domestically focused companies. Build-A-Bear Workshop illustrates both the pressure and his continuing interest in low valuations.
The retailer remained a top-10 holding, although he spent much of the year reducing the position. On July 31, it accounted for 2.7% of the portfolio, behind Cameco at 5.5% and Everus Construction Group at 3.2%. Together, the fund's 10 largest positions represented 25.4% of assets.
By October 20, Build-A-Bear's shares had fallen roughly 60% year to date, according to Google Finance. De Lisle linked the difficult consumer backdrop to high interest rates and political conditions, noting that the University of Michigan consumer confidence survey was at its second-lowest level since inception. Tariffs had also complicated sourcing suitable stuffing from places such as China.
Despite those problems, he considered the shares inexpensive at a single-digit price-to-earnings multiple. He said the business had little debt, was unlikely to suffer a collapse in sales and remained one of the country's most trusted brands.
The macro case behind his energy holdings
For de Lisle, these pressures expose the limits of stockpicking that ignores the wider economy. He argues that the disinflationary bull market from 1980 to 2020 allowed a generation of managers to buy good growth companies and hold them for decades. Bond yields kept falling until just before the vaccine announcement, helping lift growth-stock valuations.
That approach is less dependable when inflation and interest rates fluctuate more sharply and deglobalization disrupts supply chains, he said. Even a company such as McDonald's can face margin pressure from tariffs, supply blockages and fuel costs. In his view, dismissing the whole US market as expensive or speculative further restricts the opportunities investors are willing to consider.
His substantial energy exposure in 2026 reflected that broader analysis rather than a judgment about which producer was best at extracting oil. Earlier in the year, he expected conflicts in the Middle East and Ukraine to persist longer than markets anticipated.
Oil rose to about $100 in March, but energy shares did not fully reflect that move because investors expected it to fade, he said. By October 19, many oil stocks were priced higher than they had been in March. He also saw a risk that rising energy costs would feed inflation and push interest rates higher, supporting a move into lower-P/E stocks even though they could experience volatility.
"Nowadays, it's important to invest in stocks that are right for the environment you're in," he said.
Experience, market memory and fund details
De Lisle's resistance to neat historical comparisons draws on a career that began at Merrill Lynch in 1979. He later became managing director of Dean Witter International, has managed the Emmanuel College Endowment fund since 1996 and co-founded De Lisle Partners in 2005. His more than four decades of US investing span Black Monday, the dot-com collapse and the global financial crisis.
He cited Merrill Lynch's Bob Farrell: "If you live long enough, you will see every type of market once". De Lisle interprets that as a warning that investors' memories change their behavior, preventing markets from repeating in exactly the same way. Those who experienced the October 19, 1987, crash may sell earlier when conditions deteriorate, he argued. He described his generation as having something close to PTSD about Black Monday.
The VT De Lisle America Fund belongs to the IA North America sector, with Valu-Trac Investment Management Ltd serving as its authorized corporate director. Its B share classes have a 1% annual management fee and a 1.05% ongoing charges figure. The minimum investment is £1,000 or $1,000.