A narrow advance on lighter trading
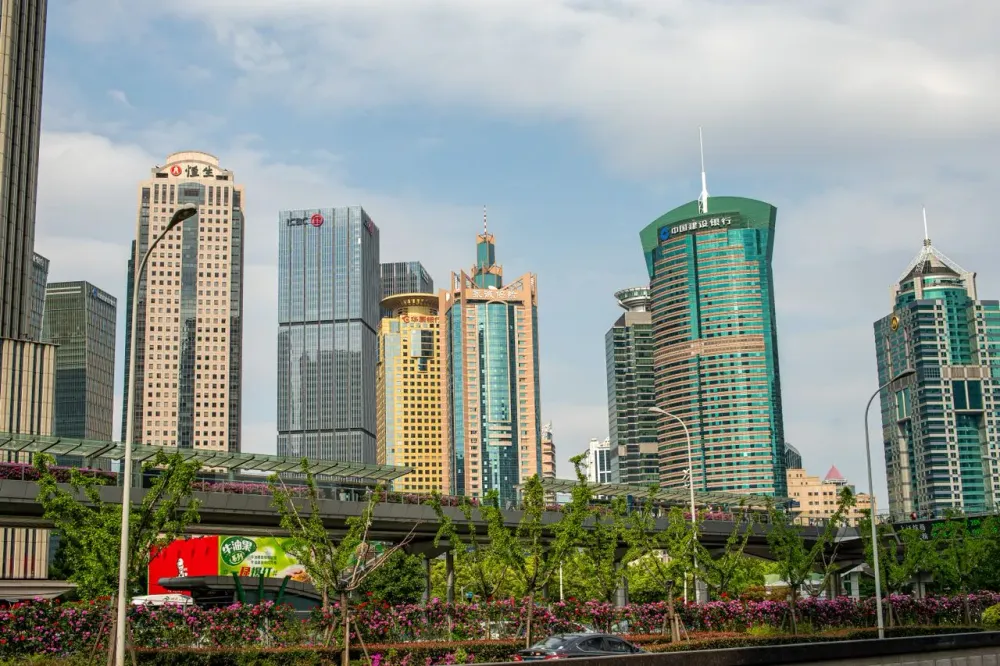
Shanghai's benchmark added 11.61 points, or 0.32%, from Friday's 3,649.18 close, recouping some of that session's 1.10% loss. Despite Friday's retreat, the index had finished last week up 1.39%, ending six consecutive weekly declines.
Other mainland indexes showed little strength. Both the Shenzhen Component and the startup-focused ChiNext lost 0.27%. The large-cap CSI 300 edged up 0.05% to 4,056.11, while the technology-focused STAR Composite advanced 0.44%.
Turnover across the two exchanges totaled about 1.48 trillion yuan, or roughly $222 billion. That was 175.2 billion yuan below the previous session's approximately 1.66 trillion yuan. The combination of falling turnover and widespread share-price declines suggested a selective shift into a few sectors rather than a broad influx of buyers.
New People's Bank of China measures had supported the previous week's recovery. BBN Times described the subsequent drop in participation as a sign that investors were waiting for more stimulus or clearer evidence of stronger demand, leaving the market sensitive to changes in sentiment, especially in overseas technology stocks.
Coal gains contrast with losses in lithium and solar
Coal stocks led the advance: China Coal Energy gained 3.33%, and Shaanxi Coal and Chemical Industry rose 2.79%. Zhengzhou Coal Industry and Electric Power and Yunmei Energy also ranked among the stronger performers. Aisino, a tax technology company, added 2.83%.
Aircraft manufacturing and ceramics stocks advanced alongside themes involving physical AI, space computing, copper-clad laminates for circuit boards and ice-and-snow tourism.
Energy metals suffered the weakest sector performance, with Tianqi Lithium and battery producer EVE Energy under pressure. Elsewhere, Sany Heavy Industry lost 3.28%, LONGi Green Energy fell 3.06%, and China Fortune Land declined 2.65%. Cement, furniture and food stocks also weakened amid caution about domestic consumption and property.
The day's inflation release showed a divergence between consumer and factory-gate prices. The National Bureau of Statistics reported that October consumer prices increased 0.7% from a year earlier, down from September's 0.9%. Producer-price inflation, by contrast, accelerated from 5.0% to 5.7%.
Energy-related industries led the producer-price increase. Coal mining and washing prices were up 36.6% year over year, while oil and natural gas extraction prices rose 35%.
Tariff extension leaves export-control deadlines unresolved
Mainland equities initially benefited from a technology rebound across Asia following the late-week recovery in US chip shares. Those early gains faded as investors considered the softer consumer inflation reading and developments in US-China relations.
Italian financial press reported during the European session that the trade truce had been extended by two months. China's State Council Tariff Commission announced on November 9 that the suspension of an additional 24% tariff on US goods would continue, with the 10% rate retained for two months beginning at 1:01 p.m. on November 10.
The tariff announcement did not resolve every deadline. According to Blooming Global, the written suspensions of China's rare-earth and graphite export controls, Announcements 70 and 72, had not been extended. Their stated expiration dates remained November 10 and November 27, respectively.
The United States had already extended three measures, Blooming Global reported. On November 6, the Office of the US Trade Representative prolonged 178 Section 301 product exclusions and the suspension of maritime logistics and shipbuilding measures through January 9, 2027. A Bureau of Industry and Security final rule published in the Federal Register on November 9 extended the suspension of the affiliates rule through January 10, 2027.
Nvidia scrutiny follows a volatile US trading week
News over the weekend of an investigation into Nvidia CEO Jensen Huang added uncertainty around technology stocks. Yahoo Finance reported that Nvidia fell more than 4% in Monday's premarket trading after its board opened an independent investigation.
In a November 8 memo, Huang acknowledged an extramarital relationship with Alice Huang, an executive at Megaspeed. An October New York Times report had linked her to a suspected Chinese intelligence operation. BBN Times also described reported links cited by US officials and said Beijing had dismissed the intelligence allegations as a smear.
Three Republican House committee chairs requested Huang's attendance at a closed-door briefing on November 18. President Donald Trump, meanwhile, publicly praised him.
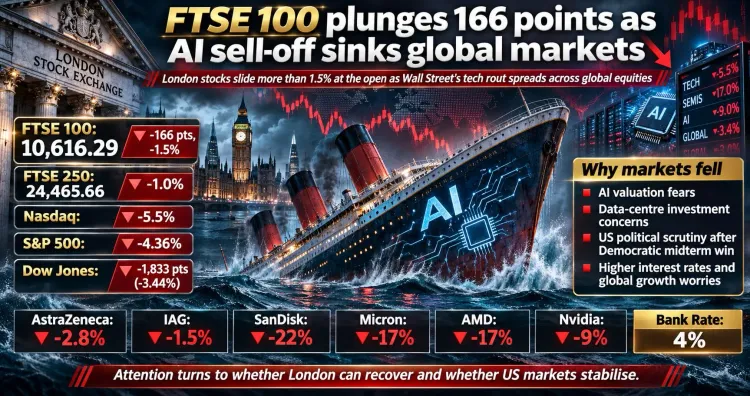
The news followed sharp swings in US markets. According to Blooming Global, results establishing Democratic control of both chambers of Congress became clear on November 3-4. On November 5, the Dow fell 3.44%, the Nasdaq lost 5.52%, and the S&P 500 dropped 4.36%. The Philadelphia Semiconductor Index plunged 12%, while Nvidia declined about 9.3%. AI stocks steadied after the USTR announced its Section 301 extension on November 6.
Japan and Western markets post stronger gains
Japan outpaced other major Asian markets as investors returned to semiconductor shares after the previous week's selloff. The Nikkei 225 rose 2.33% to 58,775.50. Hong Kong's Hang Seng slipped 0.13% to 24,448.95, while India's BSE Sensex added 0.13% to 81,106.65.
European indexes also advanced. Milan's FTSE MIB led with a 2.69% increase to 51,399.88, followed by Germany's DAX 40, up 1.73% to 26,267.19. The CAC 40 gained 1.16% to 8,233.30, London's FTSE 100 rose 1.02% to 10,782.87, and the broader STOXX Europe 600 climbed 1.26% to 656.52.
During afternoon trading in New York, the S&P 500, Dow Jones Industrial Average and Nasdaq Composite were each about 2% higher. Canada's S&P/TSX Composite gained well over 1% and moved back above 36,000.
Brent crude dropped about 4% to around $94 a barrel, while gold strengthened above $4,100 an ounce. The US 10-year Treasury yield stayed near 4.85%, below October's two-decade high of more than 5.30%.
Shanghai remains near the low end of its yearly range
Monday's advance left the Shanghai Composite near the lower end of its 52-week range, which spans 3,574.27 to 4,258.86. The index remained roughly 9% below its level a year earlier. The CSI 300 was more than 20% below its June 22 peak, putting it in bear-market territory after a historically long stretch of weekly losses through October.
BBN Times identified the 3,600 area as technical support, above the 52-week low. It placed initial resistance at last Thursday's closing level of 3,689.91 and said a recovery above 3,700 would be needed to indicate a more convincing reversal of the downtrend.
The publication characterized Monday's move as stabilization rather than the beginning of a fresh rally. Given the weak breadth and lower turnover, it favored selective exposure to policy-supported areas such as energy security and domestic technology over broad bets on an imminent recovery.
Economic releases and trade talks ahead
Investors will watch for additional monetary or fiscal support from Beijing and October activity data for evidence of whether China's slowdown is deepening. Tuesday's US consumer price report and the direction of Treasury yields will also matter for emerging-market capital flows, while developments involving Nvidia and US AI policy remain relevant to Chinese technology shares.
The unresolved rare-earth export-control deadline is an immediate focus in trade relations. Beyond that, the next US-China engagement is the APEC summit in Shenzhen on November 18-19. According to Blooming Global, it would be the third meeting between the two countries' leaders in 2026.